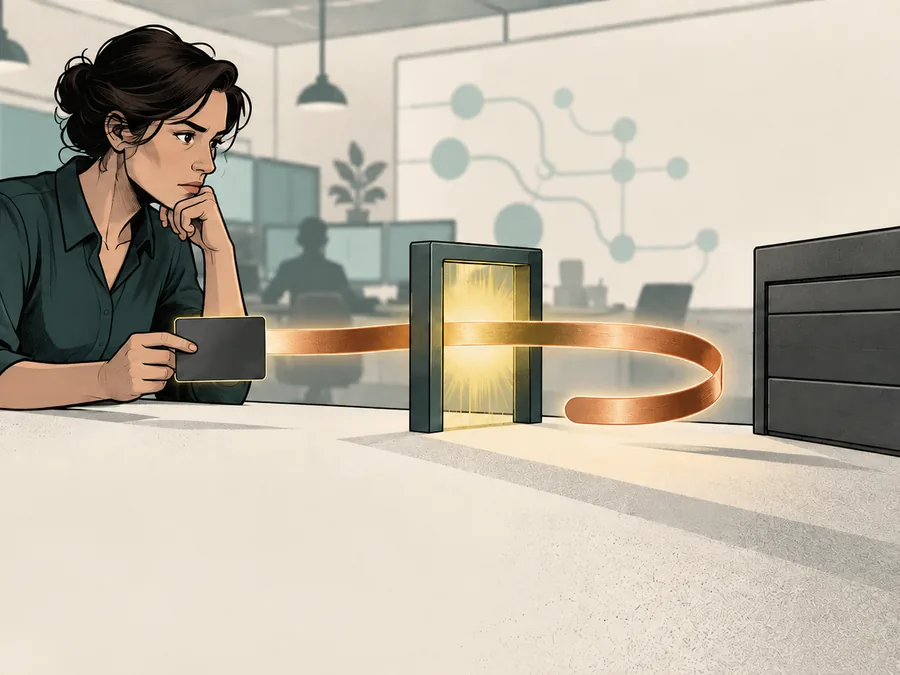
A credit card does not become a debit card when it disappears behind an e-wallet. That simple distinction is the difficult part of Britain’s gambling-payment rule. A sportsbook may see the wallet as the immediate payer, while the money used to load it may have come from a credit line. The Gambling Commission’s licence condition 6.1.2 addresses both routes: covered licensees must not accept credit-card payment for gambling, including payment made through a money service business.
The rule took effect on 14 April 2020. It is not a prohibition on every kind of borrowing, nor a claim that an operator can see a customer’s complete finances. It is a restriction on accepting a particular payment source. That boundary explains both why a cashier needs controls beyond the visible card number and why the ban cannot, by itself, settle the wider problem of gambling with borrowed money. Gambling Commission guidance · NatCen’s 2024 evaluation
The rule follows the source of the payment
Condition 6.1.2 applies to all remote gambling licences other than the named technical, software and host exceptions, and to non-remote general betting, pool betting and betting-intermediary licences. For covered operators the operative sentence is short: they must not accept payment for gambling by credit card. It explicitly includes credit-card payments routed through a money service business. Current licence condition
That covers an online casino deposit made directly with a credit card and the materially similar case in which the card first funds an e-wallet that pays the casino. The wallet is not exempt simply because its own button appears at checkout. The Commission says the operator must satisfy itself that the wallet provider prevents credit-card-funded balances from being used for gambling; if the provider has no such block, the operator must reject payments through that provider. Commission guidance on money service businesses
This is a useful distinction from our comparison of open banking and debit-card gambling payments. Those routes ordinarily move money from a bank account without turning a credit line into the funding source. Their authentication and dispute paths differ, but the credit-card restriction is not a general ban on digital payments.
A wallet button needs a funding rule behind it
An operator can identify a directly presented card type in its payment flow. A wallet adds another participant between the customer and the gambling operator. The Commission’s guidance therefore puts an assurance obligation on the operator: before taking that wallet’s payments, it must be satisfied that its customers cannot load the wallet with a credit card and then use those funds for gambling. The guidance includes payment instruments issued by the money service business itself. Commission’s MSB guidance, updated May 2024
This does not mean an operator personally inspects every earlier transaction in a customer’s financial life. It means the wallet route needs an effective provider-level block, and the operator cannot treat the presence of an e-wallet logo as proof that the rule is met. A blocked wallet transaction, a declined card and a later reversal of an apparently approved deposit can look similar on a customer screen, but they describe different payment states and causes.
The distinction also matters for payment teams. A cashier integration can be technically live while its compliance assurance is incomplete. Adding a new provider is not merely another button or a different fee schedule. It changes the controls the operator must be able to rely on. Our payment-orchestration guide examines the wider routing problem; the credit-card condition is one specific constraint within it.
The exception is narrower than the slogan
The Commission’s public guidance says the ban reaches online betting, casino and bingo, high-street and track bookmakers, and lotteries that accept payments online or by telephone. It also explains why non-remote lottery operating licences are outside this particular credit-card condition: a shop selling lottery tickets or scratchcards alongside ordinary goods is not expected to separate a card purchase item by item. Postal purchase of lottery tickets is another stated exception. Gambling Commission: preventing credit-card use
“Credit cards are banned for all gambling in Britain” is therefore too broad. The precise statement is that covered Gambling Commission licensees cannot accept credit-card payment for gambling, directly or through the specified intermediary route, subject to the licence scope and exceptions. It would be equally misleading to call a lottery retail exception a general loophole for online casino payments. Different licensed activities sit on different sides of the condition.
Nor is the rule a source-of-funds investigation. A gambling source-of-funds check asks where money came from and whether the operator has sufficient information to manage risk. Condition 6.1.2 identifies a prohibited method of payment. A customer can clear one question without clearing the other.
The evaluation found friction, not a finished solution
The policy’s aim was to add friction to the use of borrowed funds for gambling. A 2024 evaluation by the National Centre for Social Research, commissioned by Greo Evidence Insights, examined survey waves before and after the ban and interviews conducted in its 2021–23 evaluation period. Its adjusted pooled analysis found lower odds of respondents reporting credit-card gambling after the ban among all who gambled. But the pattern was not uniform: the stratified analysis found lower reported odds in no- and low-problem groups and higher reported odds in the high-problem group. The report cautions about changes in sample composition and the pandemic-era setting. Those associations should not be sold as a clean causal measure of the policy’s effect.
The evaluation also found that roughly half of post-ban respondents who reported using credit cards for gambling described indirect uses of credit. That self-report does not automatically prove a licensed operator breached the rule. The researchers explicitly noted that borrowed money can be moved or freed up in ways that the payment condition does not directly capture. Naming that boundary is not a guide to evasion; it is why a single blocked payment method cannot stand in for broader harm prevention. NatCen evaluation, executive summary
The same report records a practical implementation problem: card identification and wallet safeguards required coordination among gambling operators, payment companies and financial institutions. Its interviewed stakeholders saw mandatory rules and existing industry relationships as helpful, while identifying logistical and coordination difficulties. These are reported views from a small qualitative interview component, not a census of every operator or wallet. NatCen’s methods and findings
What a payment failure can—and cannot—tell you
A rejected deposit may be consistent with the credit-card condition, but the screen alone cannot establish that diagnosis. Identity checks, bank controls, processor decisions and account rules can also stop a transaction. A customer should not infer that a wallet is compliant merely because one payment went through, or that a gambling operator broke the rule because an unrelated debit payment failed. The player ledger and bank reconciliation are separate records from payment-method eligibility.
For the operator, the auditable question is more concrete: was this payment route allowed to carry credit-card-funded money into gambling, and what assurance supported accepting it? For the reader, the central distinction is between a ban on a *direct or wallet-mediated credit-card payment* and a ban on all borrowing. The first is in the licence condition. The second is not. Britain’s rule closes an obvious cashier path; the 2024 evaluation shows why describing that as the end of the borrowed-money problem would overstate the evidence.