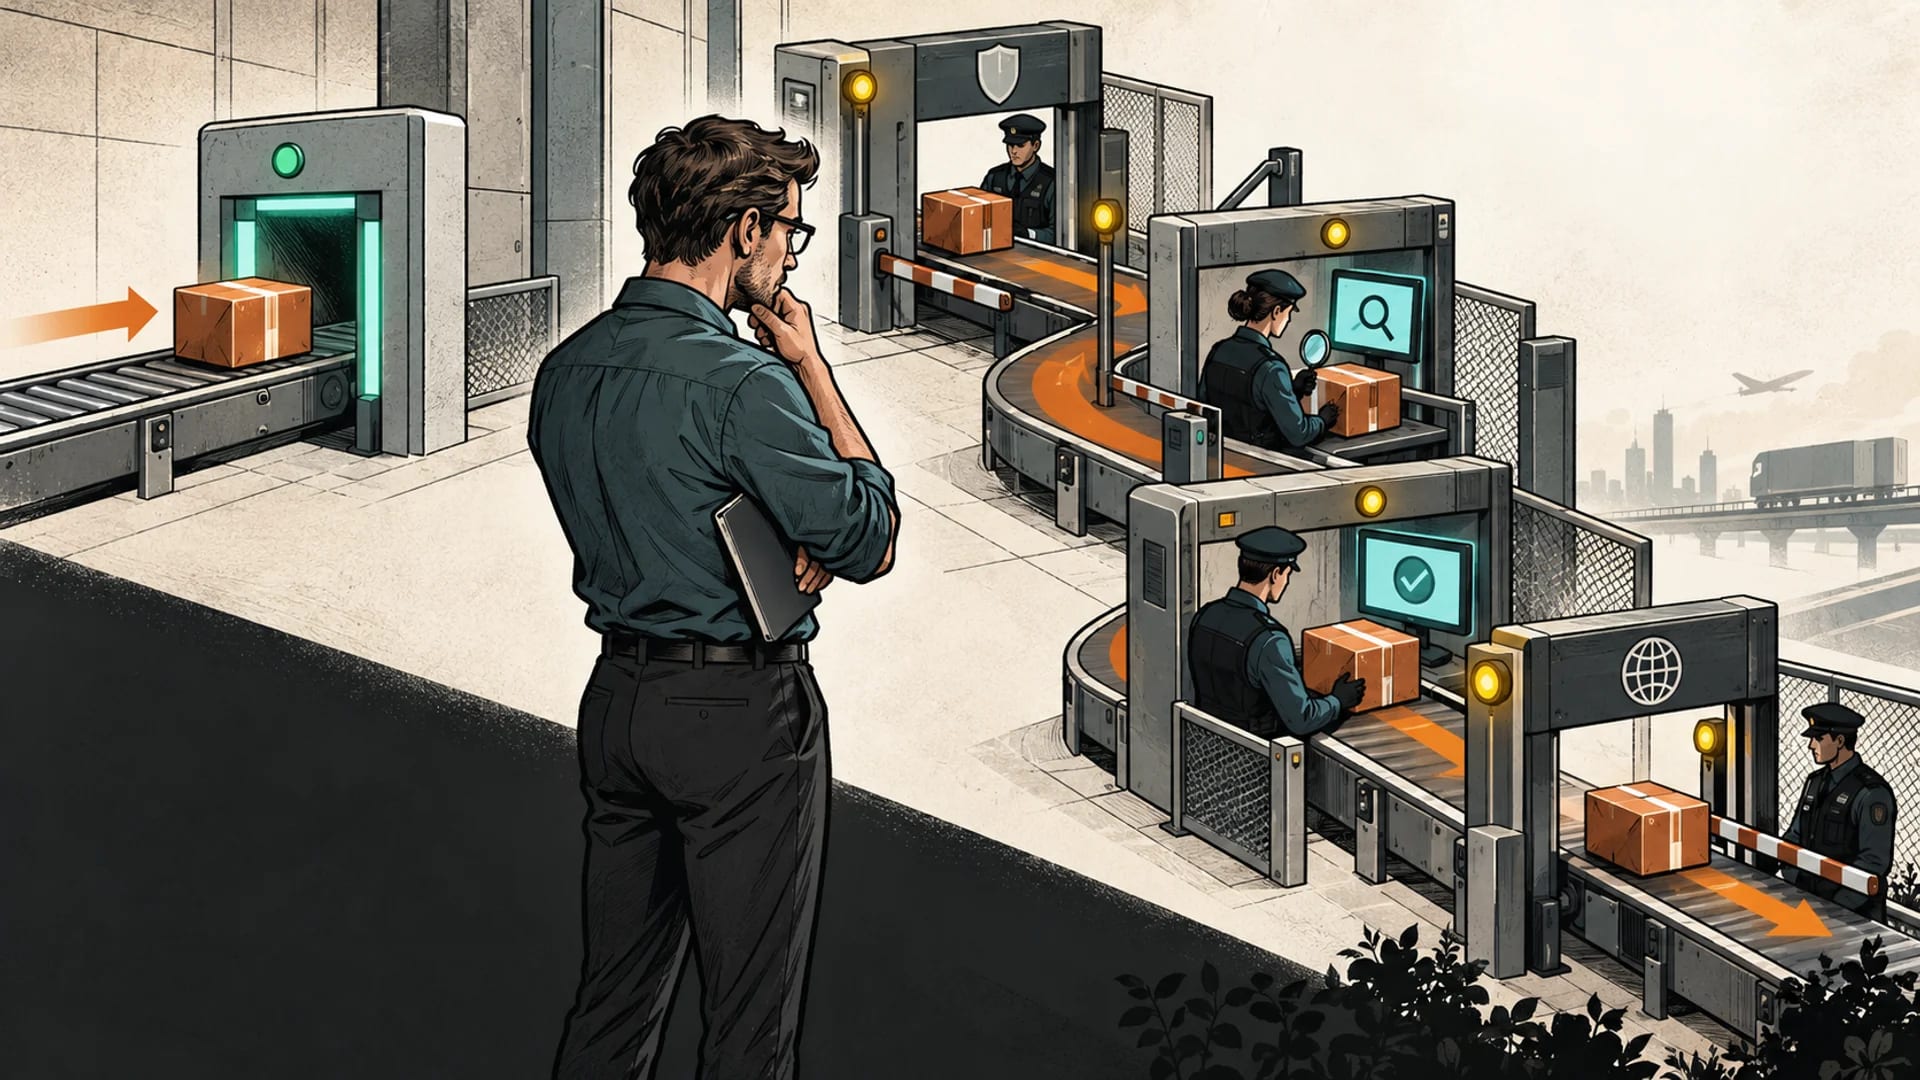
A deposit needs a quick answer to one narrow question: can this payment be accepted? A withdrawal asks several wider ones. Is the balance releasable? Is the account information complete? Can the money return through an allowed route? Has the operator sent it, and has the receiving institution posted it?
That asymmetry is the short answer. A fast payment rail can move an approved transfer in seconds, but it cannot shorten the decisions that happen before the transfer is created. “Withdrawal time” is therefore not one clock. It is a chain of clocks owned by different parties.
The British regulatory examples below concern businesses licensed in Great Britain. The OLG.ca example concerns Ontario, Canada. Neither sets a worldwide withdrawal deadline.
The deposit and withdrawal do different jobs
When a customer deposits by debit card or bank payment, the cashier requests authorisation and waits for a success or failure response. The operator may still run identity, payment and risk checks, but the product is designed to decide quickly whether play can begin.
A withdrawal reverses the direction of value and changes the operator’s task. Money is leaving the player ledger. The operator has to establish that the balance can be released, match the destination to its payment rules and create an outbound payment. Only then does the external banking or wallet network take over.
| Stage | Deposit question | Withdrawal question |
|---|---|---|
| Account | Can the payment fund this account? | Is this balance available to release? |
| Identity and risk | Can this payment be accepted now? | Are any necessary checks unresolved? |
| Destination | Which method is funding the account? | Which permitted route should receive the money? |
| Payment rail | Did the instruction succeed? | When did the approved transfer reach the receiver? |
This is why an operator saying “processed” and a bank showing “received” are not the same event. The gap between them may be small or material, depending on the rail, cut-off rules, intermediary and destination account.
Clock one: the account has to release the balance
The first delay can exist entirely inside the gambling account. A pending sports bet, a reversed card deposit, a duplicated transaction or an unresolved account restriction can affect how much is actually withdrawable. An operator also needs controls against fraud and money laundering.
Those controls are not permission to postpone ordinary verification until a customer asks for money. In Great Britain, Licence Condition 17.1.1 requires identity verification before gambling and prohibits making withdrawal conditional on information the operator could reasonably have requested earlier. It preserves requests needed at that time to meet another legal obligation.
There are legitimate exceptions. The Commission’s age and identity guidance notes that anti-money-laundering checks may still be required, and that the time needed for identification can vary. The useful distinction is not “checks versus no checks”. It is whether a check is necessary now, proportionate to the issue and explained to the customer.
In its 18 July 2024 withdrawal review, the Commission reported around 2,000 complaints a year about withdrawal delays. That is a historical complaint figure, not a current count or a payout deadline. Its July 2023 analysis had already identified withdrawals as the leading consumer complaint topic.
A restriction on further gambling is also different from a restriction on repayment. The Commission’s withdrawal expectations say customer-interaction checks for safer gambling should not, by themselves, delay or prevent withdrawals. A separate legal concern may still require investigation.
Clock two: the destination has to make sense
Operators do not always let a customer choose any convenient exit. A common control is “closed loop”: where possible, funds return to the same payment method used for the deposit. That can reduce the risk of a gambling account being used to move money between unrelated instruments.
The Gambling Commission describes withdrawal to the originating payment method as best practice in its April 2025 emerging-risk guidance. It also identifies cryptoassets as a higher-risk area that requires suitable risk assessment and controls.
Closed loop is simple as a policy phrase and messy as a customer journey. A card may have expired. A bank account may have closed. A method that accepts deposits may not support payouts in the same way. Several deposits may have come from different routes. The cashier then needs a documented fallback rather than a silent queue.
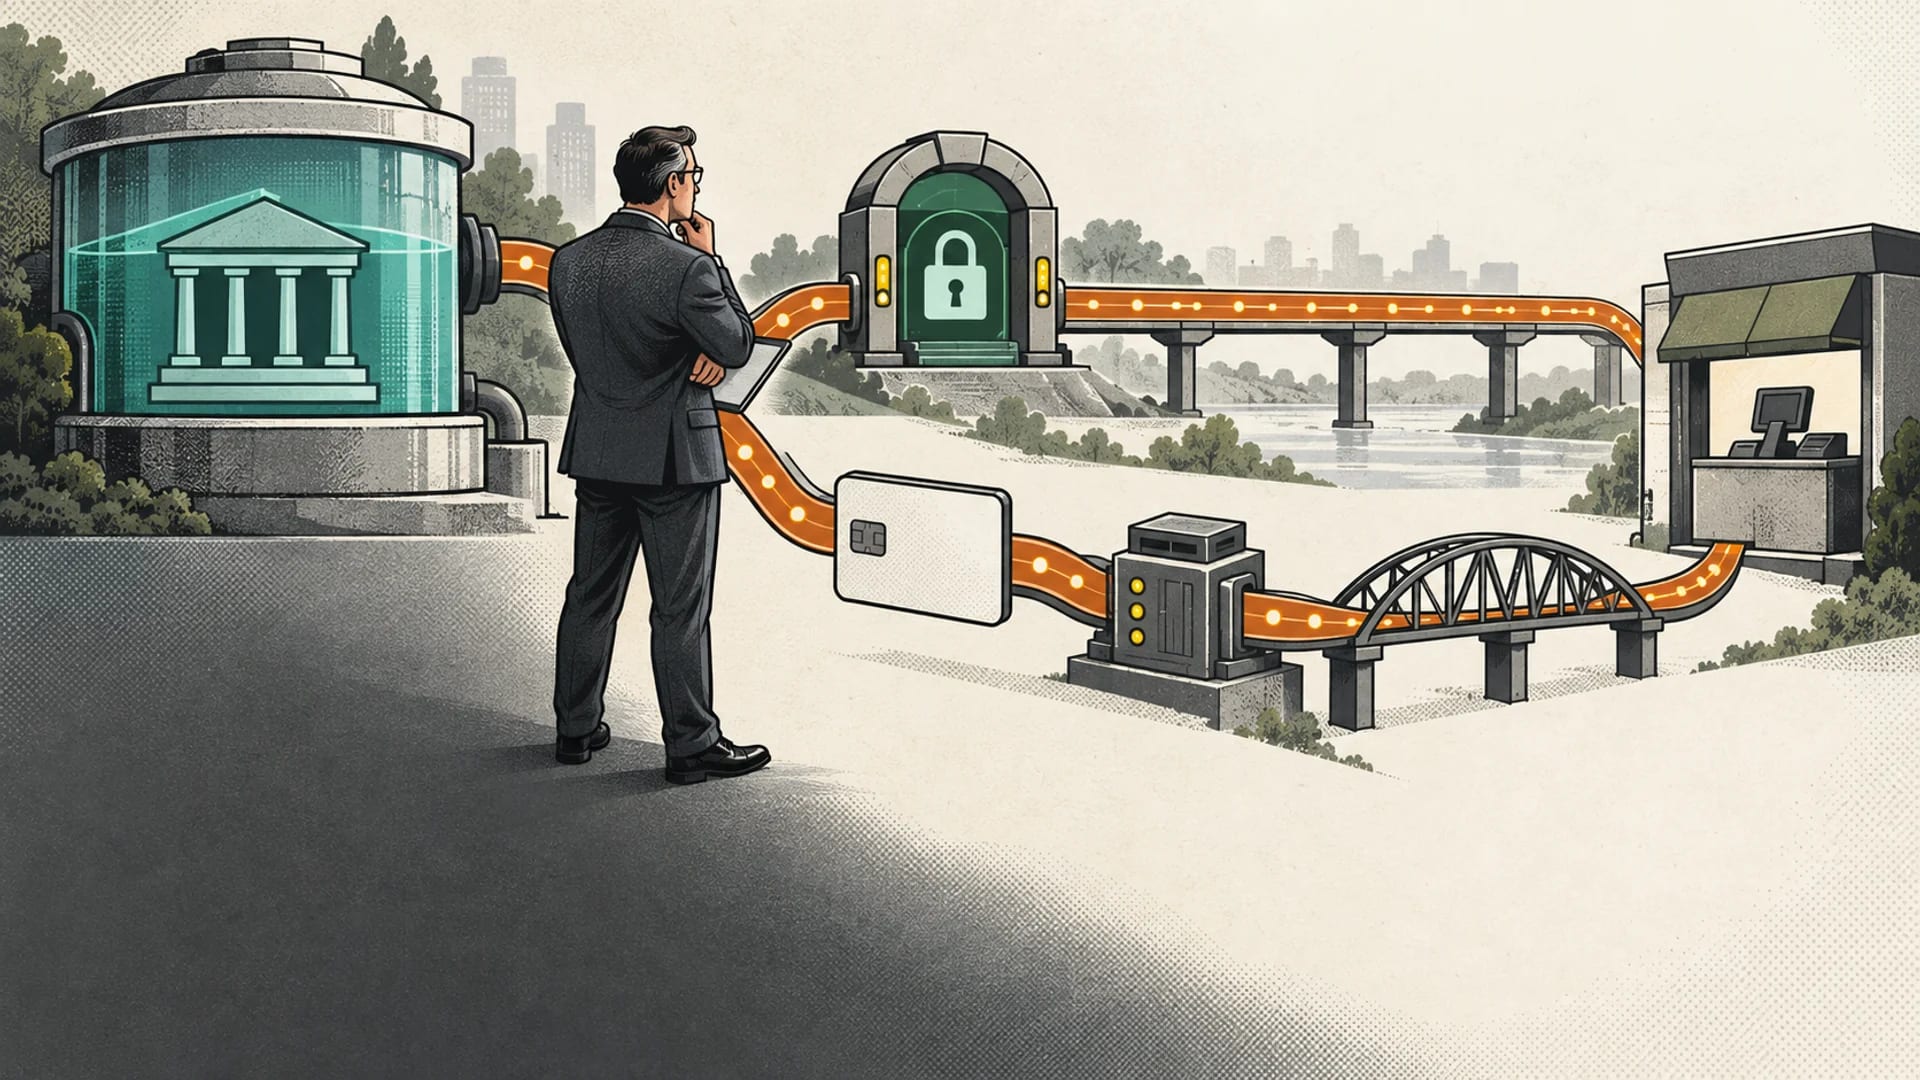
This destination problem is one reason payment operations matter. Our map of payment orchestration in iGaming shows the routing layer that sits between a cashier, risk systems, processors and banks. A withdrawal may need a different provider or set of controls from the deposit that preceded it.
Clock three: the operator has to send the instruction
“Requested” usually means the player has asked for a withdrawal. It does not necessarily mean an external payment exists. “Approved”, “processed” and “sent” can also mean different things in different products.
A useful status model would expose at least three separate states:
received by the operator;
released and sent to the payment provider or bank;
completed by the receiving route.
Collapsing these states into “pending” protects the interface from complexity but deprives the customer of the one fact that matters: who has the payment now? That is a product-design choice, not an unavoidable property of payments.
The same state problem is especially visible with crypto. A blockchain explorer may show a transfer while an operator ledger is still matching or reviewing it. Our on-chain success, cashier failure explainer separates network finality from the internal credit decision. Withdrawals need the same separation in the opposite direction.
Clock four: the payment rail has its own timing
Once a transfer is sent, the external rail determines the next part of the journey. The UK’s Faster Payments service is available continuously and is designed for payments to be processed almost immediately. Pay.UK’s January 2026 system principles describe the infrastructure, not a promise that every gambling withdrawal will arrive immediately.
For a UK bank-to-bank payment, the Financial Conduct Authority’s consumer guidance says the sending bank must get the money there by the end of the next business day. It also explains availability after receipt. That concerns the banking leg, not a deadline for a casino to complete its account review, and does not describe every card, wallet or international payout product.
Cards, bank transfers, e-wallets and crypto networks do not share one settlement path. Even within one label, providers may use different payout products. A debit-card deposit does not prove that the eventual withdrawal will be a reversal over the same technical message.
One Ontario example separates the clocks
OLG.ca’s withdrawal FAQ sets an aim of processing requests within one business day, then describes the transfer handled by banks as generally taking one to five business days, with possible delays. Bank-account verification is separate: the FAQ says it typically takes less than five business days, but may take longer. A customer still waiting for verification has not necessarily reached the bank-transfer stage.
The OLG player agreement, section 7.4, uses different wording: in most circumstances, processing can take place within three Business Days after the withdrawal conditions, including required documents, have been satisfied; longer processing may be needed. The FAQ’s one-day aim and the agreement’s conditional three-day wording should not be collapsed into a guaranteed arrival time.
Section 7.1 of that agreement specifies Canadian-dollar electronic transfers to an approved Canadian bank account held by the player, subject to exceptions. This is an Ontario example: its online casino games are for eligible players aged 19 or over, resident in Ontario and physically there when playing. It does not establish the rules for another casino or country.
Those figures are published guidance and terms, not withdrawals tested by Betting Tribune. They show why a quoted number needs a starting event, a payment method and a market. Adding the separate estimates together would not produce a reliable maximum for an individual request.
What a customer can establish without guessing
A promised range displayed by the operator is more useful than a generic industry estimate. If a withdrawal falls outside that range, the customer can ask four concrete questions:
Has the operator approved the withdrawal?
Has an outbound payment instruction been created?
Which payment method and destination were used?
Is there a reference the receiving provider can trace?
If more information is required, the operator should be able to say what it needs and why. If the payment has been sent, a trace reference is more actionable than “please wait”. Customers should preserve the request time, status changes, messages and applicable terms before using the operator’s complaint process. Regulatory and dispute routes depend on the jurisdiction.
There is no honest universal answer to “how long should a gambling withdrawal take?” The sharper question is “which clock is still running?” Good payment operations make that answer visible. Bad ones turn four separate decisions into one pale word: pending.