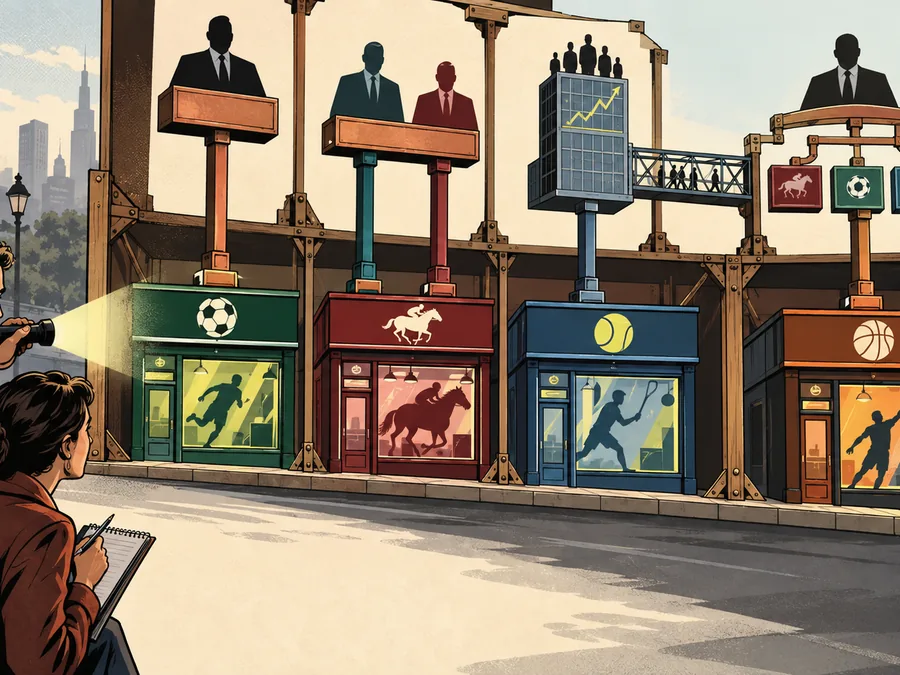
Flutter did not buy Snaitech simply to add another betting app. At the September 2024 announcement, the target brought more than 2,000 Italian retail sites alongside an online sportsbook and casino business. The shops mattered because Flutter already owned Sisal, a major Italian operator, and wanted another established route to customers in a market where its own advertising and product decisions are constrained by local rules. The shop count and strategic rationale are Flutter’s figures and claims at the time of the deal, not a fresh independent count of today’s network. Flutter’s acquisition announcement
The transaction has since moved from plan to operation. Flutter completed the €2.3 billion acquisition on 30 April 2025. In its first-quarter 2026 update, the company said it had finished moving Snai’s online platform at the end of that April. Those are observable milestones; whether the purchase earns its promised return is a different question. Flutter’s 2025 Form 10-K · Q1 2026 results filed with the SEC
A second Italian doorway
Flutter already had Sisal in Italy. Snaitech added the Snai brand, a separate customer base and a large physical distribution network. In the 2024 deal announcement Flutter described Snai as Italy’s number-three online operator, with a 9.9% online share in 2023 and 291,000 average monthly players. It also reported more than 2,000 retail sites. These were dated, company-supplied measures, not a snapshot of the merged business in September 2026. 2024 acquisition release
That combination is the acquisition thesis. A physical shop can make a brand familiar, serve a customer in person and provide a point of contact with an online product. Flutter said customers using both channels were more active and produced more revenue per player than online-only Snai customers. That comparison comes from the seller-side information cited by Flutter; it should not be read as proof that a retail visitor will become an online customer or that every shop adds profit. Flutter’s stated omnichannel case
The distinction fits our sportsbook brand ownership map. Buying an operator brings a licence perimeter, customer relationships, trading activity and physical or digital distribution. It is more than acquiring a domain or placing a new label on an existing platform.
What the €2.3 billion bought
Flutter announced cash consideration based on an enterprise value of €2.3 billion in September 2024. Its 2025 annual filing records completion on 30 April 2025, when it acquired the company that owned Snaitech, and gives consideration of roughly €2.3 billion, or $2.6 billion at the reported conversion. The company included Snai in its International segment from the acquisition date. Neither number is an annual revenue figure. Announcement · 2025 Form 10-K, business combinations
The purchase accounting shows how much of the price reflected assets other than software. The annual filing provisionally valued Snai’s point-of-sale network at $125 million. It also recognised trademarks and online customer relationships as separate intangible assets. Those are accounting estimates of acquired assets, not a market price for each individual shop and not cash proceeds from the network. Flutter’s purchase-price allocation
At announcement, Flutter expected at least €70 million in operating cost synergies from technology, content and third-party procurement after integration, with a three-year achievement timetable. The wording was forward-looking. It is not a measured saving already delivered in 2024 or 2025. The promised revenue benefit from common pricing tools and casino content is even harder to isolate from ordinary market movement. 2024 strategic case and synergy timetable
The platform move became a reported milestone
An acquisition can preserve a local brand while changing the machinery behind it. Flutter had signalled that Snai’s online customers would move to its Southern Europe and Africa technology platform. In its Q1 2026 results the company said that migration finished at the end of April and would give Snai access to Sisal’s product in the second quarter. This is Flutter’s implementation report, not an independent performance audit. Q1 2026 release filed with the SEC
Moving accounts and content onto a shared platform can reduce duplicated systems and make product updates easier to distribute. It can also create migration risk and require work to keep a recognisable brand distinct from the shared infrastructure. These are ordinary integration implications, not claims that Snai experienced a particular outage or that every promised saving materialised. The broader trade-off is explained in our piece on why sportsbooks bring their technology stack in-house. In this case the direction is slightly different: Flutter bought a whole operator and then moved its online product onto group infrastructure.
The casino side is part of that machinery too. Snai’s online offer includes gaming as well as betting. Flutter’s stated plan included access to in-house casino content and procurement advantages. As our look at why Evolution bought slot studios illustrates from the supplier side, controlling content and controlling distribution are different levers. Flutter is trying to combine both inside an operator portfolio, while keeping multiple consumer-facing Italian brands.
A larger Italian share is not the same as a deal return
The 2024 announcement projected that Snai plus Flutter’s existing Italian business would represent around 30% of Italy’s online market on completion. A projection assembled at the announcement date is not a regulator-verified 2026 share. The company’s later reporting describes Snai’s online growth and the platform migration, but group and regional results include other brands and businesses. Announcement’s market-share estimate · Q1 2026 operating commentary
Flutter’s June 2026 quarterly filing does discuss the Snai acquisition’s contribution to reported Southern Europe and Africa growth. That comparison is partly affected by when Snai entered the accounts: the prior-year quarter did not contain a full matching period. It does not supply a standalone profit-and-loss statement or a realised return on the acquisition price. Treating every rise in a regional number as proof that the shop-and-platform strategy paid off would cross the disclosure boundary. Flutter’s June 2026 Form 10-Q
The customer journey still has two front doors
There is also a consumer-product question beneath the financial one. A large retailer can use shops to introduce a digital account, but the in-person conversation and the online interface are not interchangeable. Different channel rules, customer expectations and safeguards follow each. The company can count sites and complete a software migration; it still has to demonstrate that the combination produces durable, responsibly acquired customer relationships.
For now the verified sequence is clear: a 2024 agreement, a 2025 closing and a company-reported platform migration in April 2026. The retail network was central to Flutter’s case, not a leftover from a pre-digital business. The long-term economics of putting those shops, Snai’s brand and shared technology together remain a proposition to test against future disclosures, not a result to declare in advance.