PENN Entertainment chose the 2023 Major League Baseball All-Star break to move what was then Barstool Sportsbook onto its own platform. The change went live across 16 US jurisdictions at once. It was less a software update than an engine swap performed while the business was still racing. PENN’s migration announcement
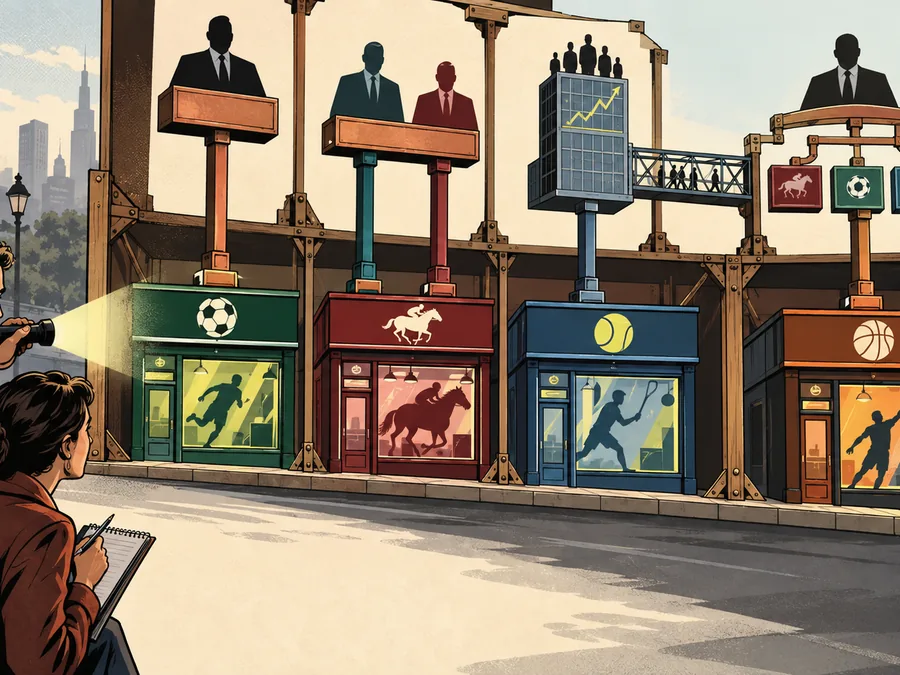
Sportsbooks bring technology in-house to control the product roadmap, pricing, promotions, customer journey and supplier economics. But “in-house” is not one switch. An operator can own the app and wallet while buying odds, or own pricing models while relying on an external platform and live-data feeds. The real decision is which layer creates enough differentiation to justify the cost and migration risk of owning it.
PENN, DraftKings and Entain reached that decision through three different transactions. Their choices make the trade-off more useful than the label.
One sportsbook contains several technology decisions
A sportsbook stack joins systems that do different jobs. The boundaries vary by company, but five layers explain most ownership claims.
| Layer | What it controls | A common sourcing choice |
|---|---|---|
| Customer product | App, web interface, search, bet slip and promotions | Built by the operator or supplied as a front end |
| Account and wallet | Login, player record, balances, limits and payments integration | Proprietary platform, third-party player-account system or a hybrid |
| Betting engine | Bet acceptance, ticket record, settlement workflow and market controls | Turnkey sportsbook or operator-owned platform |
| Trading and pricing | Odds, models, liabilities, limits and market creation | Managed trading, external odds feed, acquired specialist or internal team |
| Event data | Scores, incidents, lineups and official or secondary feeds | Almost always connected from outside rights holders and data suppliers |
Owning one row does not imply ownership of all five. Nor does using a supplier make the visible sportsbook a mere skin. A brand may control customer acquisition, product design and compliance while outsourcing the betting engine. Our guide to white-label sportsbook operations separates the brand, technology provider and accountable licence holder.
This layered view also prevents a common mistake in acquisition announcements. “Vertical integration” describes a direction and a set of capabilities. It does not prove that every dependency has disappeared.
PENN bought a migration window
PENN’s July 2023 release said the company moved Barstool Sportsbook and Casino to its proprietary platform simultaneously across 16 jurisdictions. It connected the project to its acquisition of theScore and described control of the end-to-end customer journey, risk and trading, promotions and product development as the objective.
The timing shows what operators buy when they bring a platform inside. One coordinated release had to preserve accounts, balances, jurisdictional configurations and betting operations while changing the machinery underneath them. The company said the new stack added more markets, deeper media integration, faster loading and improved cash-out availability. Those are PENN’s reported product outcomes, not an independent measurement of the migration.
The brand above that platform did not remain fixed. PENN later licensed ESPN BET, then agreed to end that arrangement and move the US sportsbook to theScore Bet. The November 2025 filing terminated the ESPN trademark use and integrations while stating that each party kept its own end-user data. PENN’s SEC filing on the ESPN BET termination
That sequence is revealing. A sportsbook brand and its distribution partner can change while the underlying operating platform survives. The distinction between brand, owner and commercial partner also appears in our sportsbook ownership map.
DraftKings bought the platform it had depended on
DraftKings took a different route. In April 2020, it completed a business combination with SBTech, which supplied sportsbook platform, trading and risk-management technology. DraftKings described the combined company as a vertically integrated US sports betting and online gaming operator. The closing announcement filed with the SEC
The company’s later registration statement set out the operating logic more plainly. DraftKings planned to migrate its consumer sportsbook to SBTech’s proprietary risk and trading platform, reduce third-party platform fees and remove reliance on an outside platform for that part of the product. It also intended to keep serving other branded operators with the acquired technology. DraftKings’ 2020 registration statement
This was not a clean choice between “build” and “buy”. DraftKings bought a supplier, inherited its software and staff, then had to integrate both into the operator. Acquisition accelerated ownership, but it also converted a vendor relationship into a long-term integration programme.
The economics changed at the same time. A platform fee could become internal engineering, infrastructure and support cost. That may improve unit economics at sufficient scale, but the cost does not vanish. It changes shape and moves onto the operator’s payroll and capital plan.
Entain bought a narrower capability: pricing
Entain’s 2023 acquisition of Angstrom Sports shows a more selective version of vertical integration. The company paid £81 million upfront with contingent payments of up to £122 million for sports modelling, forecasting and data analytics capabilities. Entain said the target would bring US sports pricing, risk and analytics in-house, with a particular focus on parlays and in-play products. Entain’s Angstrom acquisition announcement
One year later, Entain reported that Angstrom’s integration had expanded BetMGM’s Major League Baseball and National Basketball Association markets and supported an in-house same-game-parlay product. It also reported that weekly MLB same-game-parlay volumes had doubled and active users placing those bets were up 40% year on year. Entain’s 2024 interim report
Those figures are company-reported product metrics. They do not isolate Angstrom as the sole cause, and they do not establish whether the purchase earned an adequate return. What they do show is the operating connection Entain wanted investors to see: ownership of modelling was meant to create more combinations and faster product iteration, not merely replace an invoice from a supplier.
Pricing is also only one layer. Even an internal model needs reliable event inputs. Our account of the live sports data pipeline follows the external rights, collection and feed relationships that can sit upstream of an operator’s own trading system.
Suppliers are unbundling instead of disappearing
Operators buying technology have not made sportsbook suppliers obsolete. Suppliers have changed the size of what they sell.
Kambi currently presents three product shapes: a complete turnkey sportsbook, a flexible platform that can accommodate an operator’s own trading, and selected modules for companies already running proprietary platforms. Kambi’s product portfolio Its 2025 annual report lists Turnkey Sportsbook alongside Odds Feed+, Managed Trading, Bet Builder, Front End and Sportsbook Platform as separate products. Kambi’s 2025 annual report announcement
That catalogue is a response to the same ownership problem. A new entrant may need a full operation. A larger operator may want its own customer experience but still buy pricing or trading. A vertically integrated company may purchase only a specialist module for a sport, market type or jurisdiction.
The supplier relationship becomes smaller and more specific rather than disappearing. That can reduce migration scope and preserve access to specialist expertise, while leaving the operator dependent on another company at a deliberately chosen seam.
What control changes—and what it cannot guarantee
The commercial case for ownership usually rests on four kinds of control.
| Control gained | Possible benefit | Cost or limit that remains |
|---|---|---|
| Product roadmap | Features and markets can be prioritised without waiting for a shared supplier release | Internal teams must design, build, test and support them |
| Pricing and risk | Models can be tuned to the operator’s markets, liabilities and product ideas | Bad data or a weak model is now the operator’s problem |
| Customer and promotion logic | Wallet, media, loyalty and offer systems can be connected more closely | Privacy, licensing and responsible-gambling controls still constrain use |
| Supplier economics | External platform fees may fall at sufficient scale | Payroll, infrastructure, migration and opportunity costs rise |
Control is not the same as resilience. A proprietary system can still fail, receive delayed data or suspend a market. The useful operational question is whether the owner can detect the fault, stop unsafe acceptance, recover the event state and explain the result. Our market-suspension explainer follows that control when pricing confidence disappears.
Ownership also does not establish product quality by itself. PENN, DraftKings and Entain described the strategic benefits they expected. Each claim still has to be tested against delivery, customer outcomes and the full cost of maintaining the capability.
The migration bill arrives first
Supplier independence has an awkward cash-flow order: migration risk and duplicate running costs arrive before the hoped-for savings.
An operator may need to run old and new systems in parallel, reconcile wallet and ticket records, certify changes in multiple jurisdictions, retrain traders and support teams, and plan rollback paths. Open bets are especially sensitive because a platform migration cannot change the contract already recorded with the customer.
Scale therefore changes the answer. A small operator may gain more from a supplier’s shared trading, compliance integrations and round-the-clock support than it would save by reproducing them. A large operator with enough volume and a distinctive product thesis may justify a permanent modelling and engineering organisation.
The middle is not failure. A hybrid stack can keep commodity infrastructure outside while concentrating ownership around the capability the operator believes will move conversion, margin, speed or differentiation.
The decision is which constraint to own
PENN wanted control of a complete operating platform. DraftKings acquired the supplier behind a platform it intended to rely on. Entain bought a specialist modelling layer. Kambi now sells operators a range from turnkey to modular components.
Taken together, those cases reject the simple story that mature sportsbooks inevitably build everything themselves. The more useful questions are narrower:
Which product constraint is currently controlled by a supplier?
Would ownership create a customer or trading advantage that competitors cannot buy as easily?
Does the operator have enough scale to carry permanent engineering, trading and compliance cost?
Can the migration preserve balances, open tickets, audit history and jurisdictional controls?
Which external data, payment and regulatory dependencies will remain afterwards?
“In-house” sounds like independence. In practice, it is a decision to move one boundary. The strongest operator is not the one with the longest list of proprietary systems. It is the one that knows which constraint is worth owning—and which supplier relationship is still doing valuable work.